What Hongkongers need to know about the latest changes to the MPF scheme
Hong Kong employees will have better control over the management of their compulsory retirement savings under the Mandatory Provident Fund (MPF) starting from December 21.
The new “full portability” mechanism comes after another major change in 2024, when the authority launched the eMPF platform, a centralised electronic platform to standardise, streamline and automate the administrative processes of the MPF scheme, marking the start of the MPF digital era.
The South China Morning Post looks at the details of the latest changes and how they will affect employees.
1. What is MPF?
The MPF System, set up in December 2000, is an important part of the city’s retirement protection framework, enabling residents to save up for retirement.
Under the scheme, employees and employers are both required to make mandatory contributions of 5 per cent of the employee’s relevant income into the employee’s MPF account, subject to the relevant minimum and maximum income levels.
Employers must make mandatory contributions to each employee from their own funds. They must also deduct the employee’s contributions from his or her income.
For monthly paid employees, the current minimum and maximum relevant income levels are HK$7,100 (US$905) and HK$30,000 respectively.
2. What are the changes?
Starting from December 21, employees will be allowed to move their entire MPF savings to a different provider once every calendar year.
The arrangement, known as “full portability”, will allow eligible users to transfer both employer and employee contributions to their preferred MPF scheme.
The current system follows a “semi-portability” arrangement, meaning only the employee’s portion can be moved.
The new arrangement will be carried out in two phases. The first phase, starting from December 21, will cover employees who joined the workforce or changed jobs on or after May 1, 2025.
The second phase, with the implementation date to be confirmed, will cover those who started their current employment before May 1, 2025.
As employers’ MPF contributions can still be used to offset payments for long service or severance for the period before May 1, 2025, a legal amendment will be needed to enable “full portability” to be implemented for all employees.
The government is expected to submit the legal amendment on the second phase of the arrangement in mid-2027.
3. How will employees benefit?
According to Mandatory Provident Fund Schemes Authority chairwoman Ayesha Macpherson Lau, the new arrangement will give residents better control over their MPF, encouraging them to manage their retirement savings more actively.
Lawmaker Chau Siu-chung, who represents the labour constituency, said on Monday that staff would have the freedom to place their money with their preferred provider.
“They can transfer their MPF savings to a trustee whom they deem to have lower administration fees, better service or higher returns,” he said.
He added that individual trustees could lower their administrative fees if more competition was introduced for those services.
4. How can employees move their MPF savings to another provider?
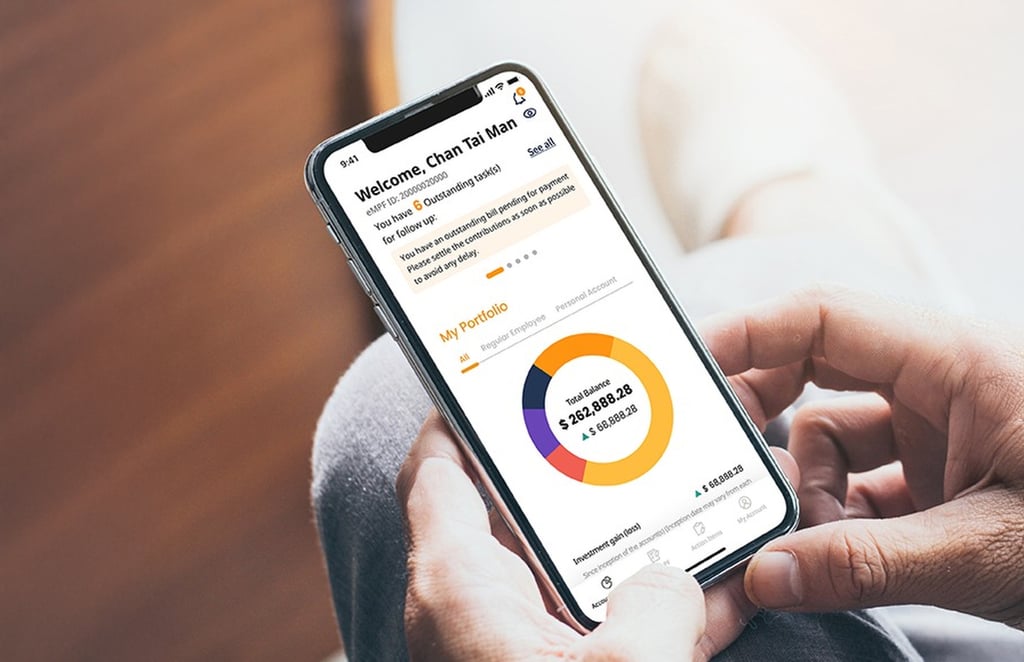
With the launch of eMPF, a centralised and digital system, employees can submit their transfer instructions via the platform.
MPF derived from employees’ and employers’ mandatory contributions can be transferred to the same scheme, or to two different ones.
Eligible employees who wish to transfer their MPF this year can make the transfer from December 21 to 31.
Chau said the digital platform is expected to simplify the transfer process. Previously, employees had to visit the offices of service providers in person to handle the procedure.
Since the launch of eMPF in June 2024, more than 2.3 million members have already registered to use the digital platform.
5. How many are eligible for the new change?
About one million employees who joined the workforce or changed jobs on or after May 1 last year will be eligible for the first phase of the new arrangement when it starts on December 21.
When the second phase is launched, a total of around 2.6 million employees could become eligible, according to a government document released last year.
6. How does ‘full portability’ affect employers?
The authority says employers will not be affected. They do not need to be involved in the process of transferring MPF, and administrative arrangements under the scheme will remain unchanged.
7. What is the advice for employees?
Lau reminded members to avoid “switching for the sake of switching” and refrain from transferring funds too frequently, as the MPF was a long-term investment.
Before taking advantage of full portability, scheme members should weigh various factors, carefully compare fund choices, performance and fee levels of different MPF schemes, and make prudent decisions based on their stage in life, investment goals and risk tolerance, she said.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.